- An emergency fund is money set aside exclusively for unexpected costs
- Financial experts recommend saving three to six months of essential expenses
- Emergency funds must stay liquid and low-risk, unlike investments, which are designed for long-term growth
- Keep your emergency fund in an instant-access and insured savings account
Life is full of unexpected events, and anyone who keeps their finances in check should build an emergency fund to stay financially ready for anything that comes their way.
Setting aside money for emergencies in 2026 is getting easier with bank deposits and strategic investments that protect liquid money from inflation.
What does an emergency fund mean?
An emergency fund is the amount of money set aside for unforeseen situations that you can use without affecting your long- or short-term investments. These funds are liquid capital that can be easily accessed and are stored in savings accounts.
As the name suggests, you use them primarily in times of crisis, when cash inflow is low, and you urgently need to cover expenses. Think of it as a piggy bank, like in the old days, when you only broke the bank when you really needed the money.
Regardless of whether you invest or not, having a safety net is important, as it clears some of the stress for uncertain times.
What types of emergencies to prepare for
Emergency situations mean you need to cover your most basic needs, such as making a living, having a roof over your head, staying healthy, and putting food on the table. Such emergencies can happen at any time, and without money set aside, you won’t be able to meet your needs.
Some examples of emergencies you have to prepare for include:
- Losing your jobs
- Having a family emergency
- Urgent home repairs
- Sudden rent or utility price increases
- Purchasing groceries when there is no income coming in
Why is saving different than an emergency fund?
Saving and creating an emergency fund serve different purposes: saving is for money you don't need right now, but for a bigger purchase or retirement. An emergency fund is exactly what it means - it's designed to cover emergencies.
Keep the fund separate so you can use it in urgent situations. That means it covers 3 to 6 months of salary and is kept untouched for the unexpected. When it comes to savings, the general rules apply differently for everyone. Some can save more, some use automated tools, and others save for retirement.
People often confuse the two, and that creates risk. When you take money from an emergency account for a non-emergency expense, you might find yourself short when a real emergency hits. The same applies to your savings, which can hurt your long-term goals if you keep cashing out to pay for unplanned events.
How much should you add to your emergency fund?
The amount you need in your emergency account is between 3 and 6 months of salary. Financial advisors consistently recommend this. It shouldn't be so high that it strains your budget, and you should be able to reach it within a year of saving. In most cases, you can reach it faster.
To see whether these general recommendations still apply in 2026, we conducted our own research on how much money to save for your emergency fund. We analyzed Reddit data from 489 self-reported answers in discussions about personal finance, money, and the FIRE lifestyle. The sample data recorded answers between Aug 2nd 2021 and May 25th 2025.
We collected the answers from the public Arctic Shift Reddit archive. We kept only top-level replies to the question. From our analysis, we gathered 86 answers that gave a dollar amount; 269 gave months of expenses covered (66 gave both). Here’s what our findings showed.
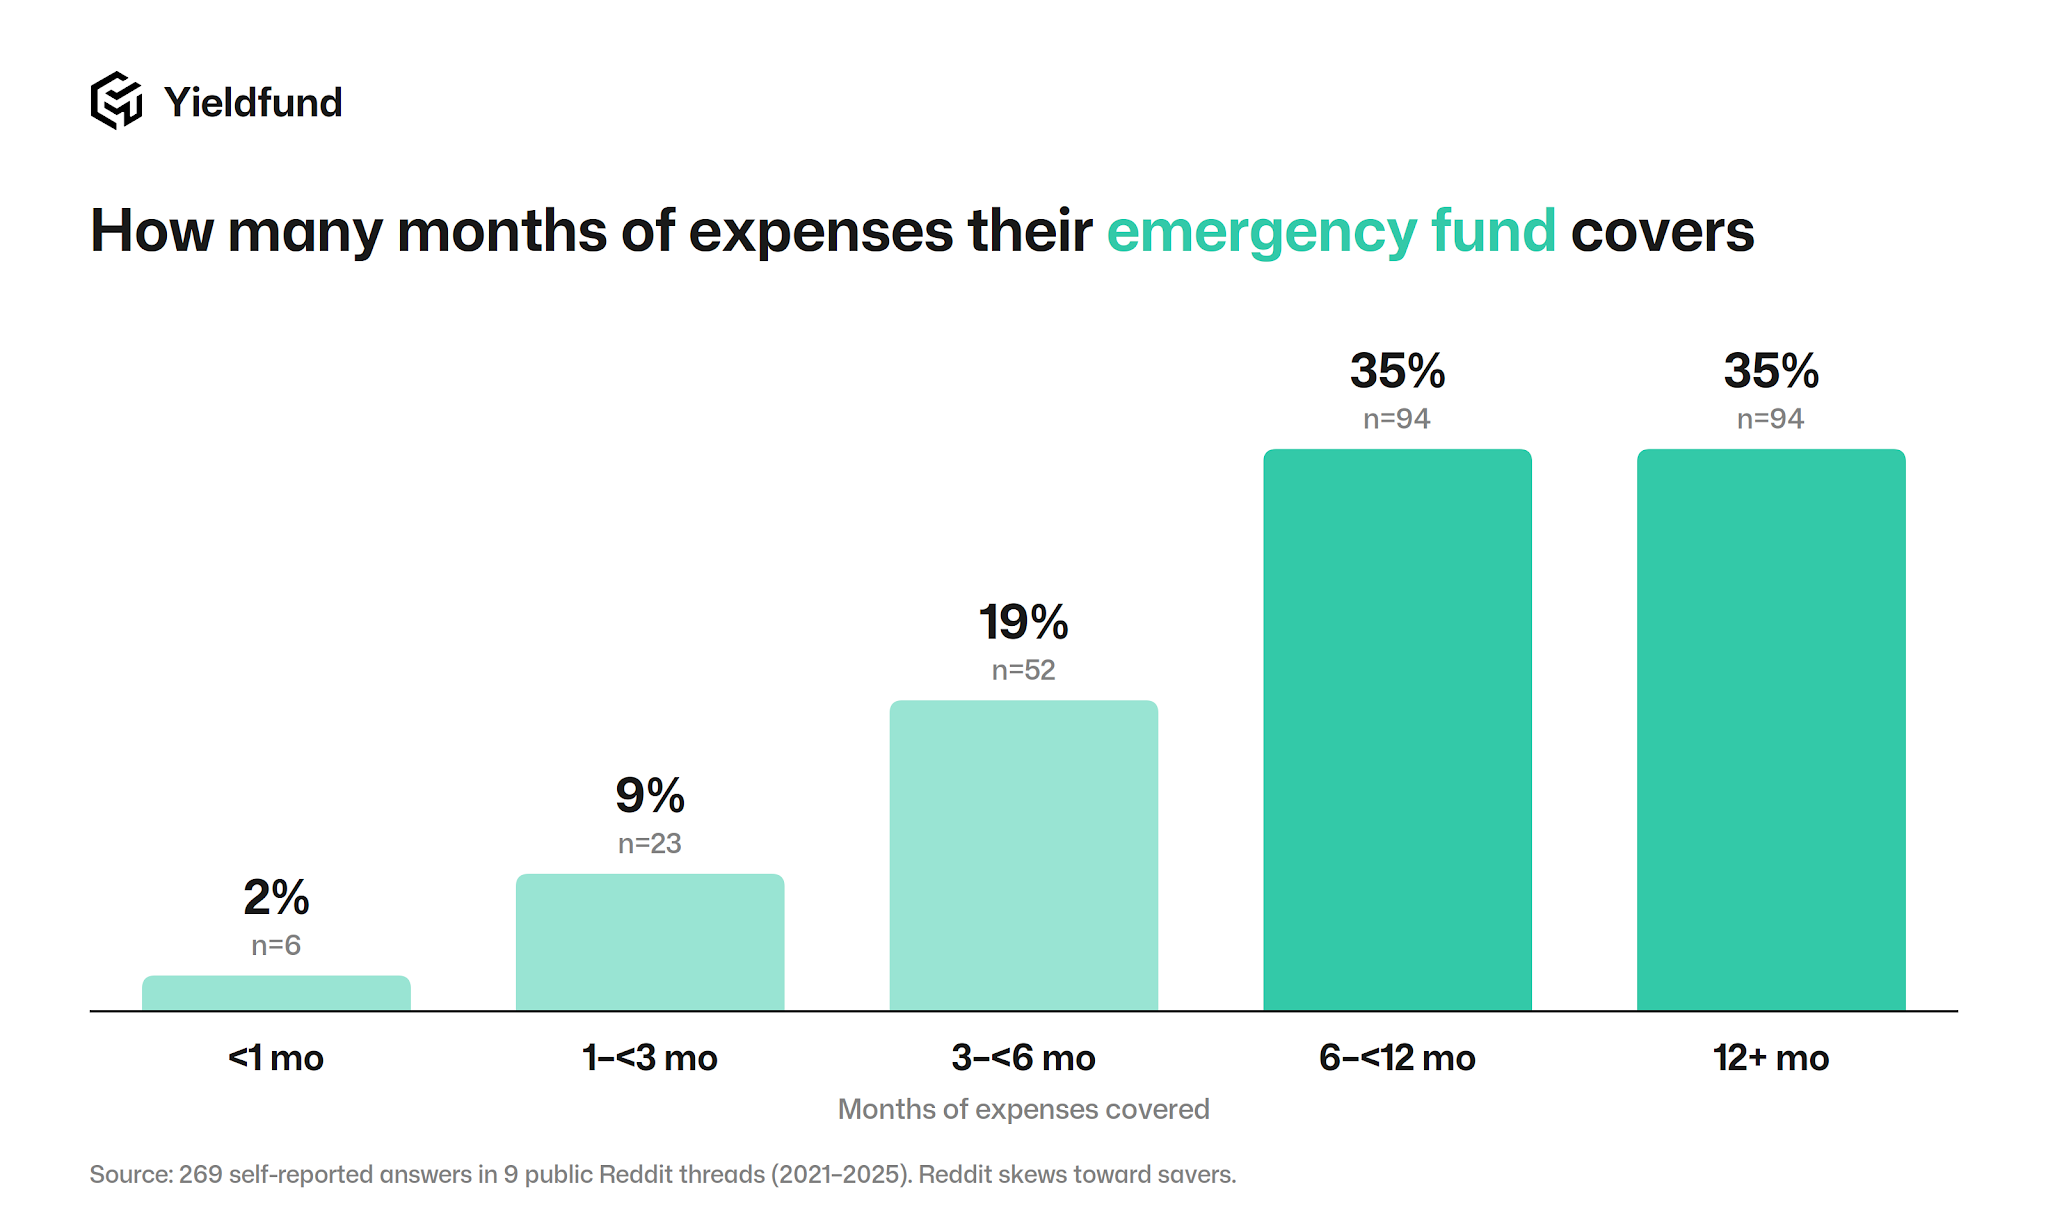
Our study shows that over 89% of respondents have 3+ months of expenses saved, while 70% of respondents have 6+ months saved. Only 35% of respondents have more than 12 months of living expenses saved in their emergency fund.
Interestingly, the amount saved also matters: over 42% of respondents reported having more than $25,000 in their emergency accounts, and 72% reported having $10,000 or more for emergencies.
We also identified what people use their savings for: about 62% of respondents cited job loss or lost income.
The data show that Reddit users engaged in personal finance tend to save. This is not a national average and only reflects a small sample of data.
Can your emergency funds be in stocks
Emergency savings need to be liquid and easily accessible, and the stock market isn’t reliable for keeping your portfolio's value consistent. When the market crashes or corrects, prices can drop by 5% or more at times.
If that is the time you have to cover an emergency, two things can happen:
- You have less money than you added to the stock market
- You’re less likely to cash out from the stock market at a loss.
An alternative to keeping money in the stock market is using high-interest savings accounts or a regular savings account. While the upside is much smaller, you can access capital immediately without significant losses.
Is it possible to save $5,000 in 3 months?
We all want to know what’s the fastest way to build our emergency account. Saving $5,000 is possible, but you need to start budgeting and cut down on your expenses. The amount is, however, considered high for most people, especially if you work on a minimum wage and have high expenses.
If $5,000 is your monthly salary, you can tighten your belt for three months and start saving everywhere. This means no more eating out, cooking efficiently, avoiding unnecessary shopping, keeping costs to a minimum, cutting subscriptions, and even saying no to a few outings.
In most cases, people can set aside only 20%, but can reach their goal without investing and keep it by keeping expenses low. Consider how much you earn and how much you want in your budget, then create a plan.bud
5 steps to build an emergency fund
Building your emergency buffer involves a lot to consider, including your " real " essential expenses, how you manage inflation, and how to differentiate between rainy-day funds and an emergency fund. Here's how you should approach it.
1. How Many Months the Fund Should Cover
Start by adding your essential monthly expenses to a spreadsheet. This includes housing, groceries, insurance, transportation, utilities, and child expenses. Calculate the total and also note down how much of it is actually essential and what is discretionary (such as dining out, bars, or subscriptions)
Now multiply your total essential expenses by the number of months to find your target. For example, if your essentials add up to €2,300 and you're targeting a 6-month emergency fund, then your goal is €13,800.
2. Choose your saving tools
The fund builds over time, so it's important to set aside money from your paycheck p consistently. Use the recurring function from your bank to set aside 15-20% of your salary into a dedicated account with the name: Emergency. Another way to build the fund is to use round-up features that redirect spare change from everyday spending to the same account.
3. Select the currency you want to use
You have to decide on the currency you want to save in. If you're paid in a currency other than the Euro, consider inflation and conversion fees. Match the currency to where your essential expenses are billed.
4. Invest to avoid losing money to inflation
Keeping money tucked away is good for instant access, but it doesn't have to sit idle. Add money to accounts that pay some interest. Even low-interest accounts remove some of the losses. Another option is to use short-term certificates of deposit where money stays liquid but still earns interest to offset inflation.
5. Segment between savings and emergency fund
Keep your emergency fund separate from both your everyday spending account and your investment capital. This separation reduces the temptation to dip into emergency savings for non-urgent expenses and keeps your investment strategy unaffected by short-term cash needs.
How to offset inflation and where to keep your emergency fund
An emergency fund must be available; to be useful in urgent cases, it must also be safe, accessible, and offer modest growth. Thus, the priority is to keep capital safe without taking unnecessary risk. Here's what we recommend you look for:
- Instant or near-instant access: You need to withdraw funds quickly without penalties or waiting periods.
- Deposit insurance: Look for accounts protected by Deposit Guarantee Schemes (DGS) in the EU, which cover up to €100,000 per person, per bank.
- Competitive interest rates: High-yield savings accounts or instant access cash deposits can help offset inflation for Euro deposits.
- Separation from spending accounts: Keeping your emergency fund in a separate account creates a natural barrier that discourages impulsive spending.
Before you get started
Before diving into investment strategies, view your emergency fund as the foundation that makes those investments sustainable. Having one in place removes financial uncertainty and gives you the confidence to invest without hesitation.
If you already have an emergency fund in place and are ready to put your remaining capital to work, Yieldfund offers accessible quantitative trading plans with weekly payouts sent directly to your wallet. To learn more, contact our investment relations team here.
FAQ
Should my emergency fund be invested for higher returns?
No, an emergency fund needs to remain liquid and stable, so it should stay in an insured, instant-access savings account rather than in stocks or crypto.
How is an emergency fund different from investment capital?
An emergency fund covers unpredictable, urgent expenses and must be accessible immediately, while investment capital is allocated toward long-term growth.
A common rule of thumb is to keep 3–6 months of essential expenses in your emergency fund. If you're income is irregular or tied to volatile investments aim for close to 6–12 months.
About the authors
Written by
Vlad Hategan
SEO content writer
Writes the articles in the Yieldfund knowledge base.
Dutch, English, Romanian
Translated by
Patricia Van den Kerckhove
Senior content translator
Translates and reviews Yieldfund's content in Dutch.
Dutch (NL & BE), French, English